Knowing what benefits you have following a serious car accident is key to ensuring you get enough money to cover all of your expenses.
When a life-altering crash suddenly occurs, your last thought is about what coverage you have and what benefits you can receive. Instead, you concentrate on who will pay for the vehicle, who will pay for the medical bills because your body is hurt, and how you can ever afford an attorney now because you can’t even go back to work.
However, there is always light at the end of the tunnel: you must absolutely know about the following benefits.
Medical Coverage
First, get a copy of your declaration page. I need you to find out what your PIP coverage is and whether it is coordinated or an opt-out. The average policy in Michigan is $250,000 in medical coverage and this is enough coverage to undergo about 6 months of treatment, a few injections, and possible surgery.
When you call your insurance company and report an injury, the insurance carrier will give you a claim number. KEEP THIS NUMBER AND GIVE IT TO EVERYONE. Give it to the ER, the Primary Care Doctor, and all treaters. All medical bills will have to go through that claim number and in some instances, the treatment can be billed under your health insurance. If you retain a lawyer, make sure to give it to them, too.
In many accidents, you are able to get the following benefits:
- Household Services / Replacement Services: These are similar to having someone do chores around the home and you can claim up to $20 a day.
- Attendant Care Services: These are nursing care services such as taking a shower, helping with hygiene, transferring and repositioning. The average claimed is $20 an hour, but if the person has any medical certifications, then you can get up to market rate for every hour.
- Mileage: You can get reimbursed for mileage up to the IRS reimbursement amount, which changes nearly every year.
- Wage Loss: You can get paid up to 85% of your wages if you are a W2 employee. If you are a 1099 employee, you can get up to 85% of the net (after expenses).
Collision
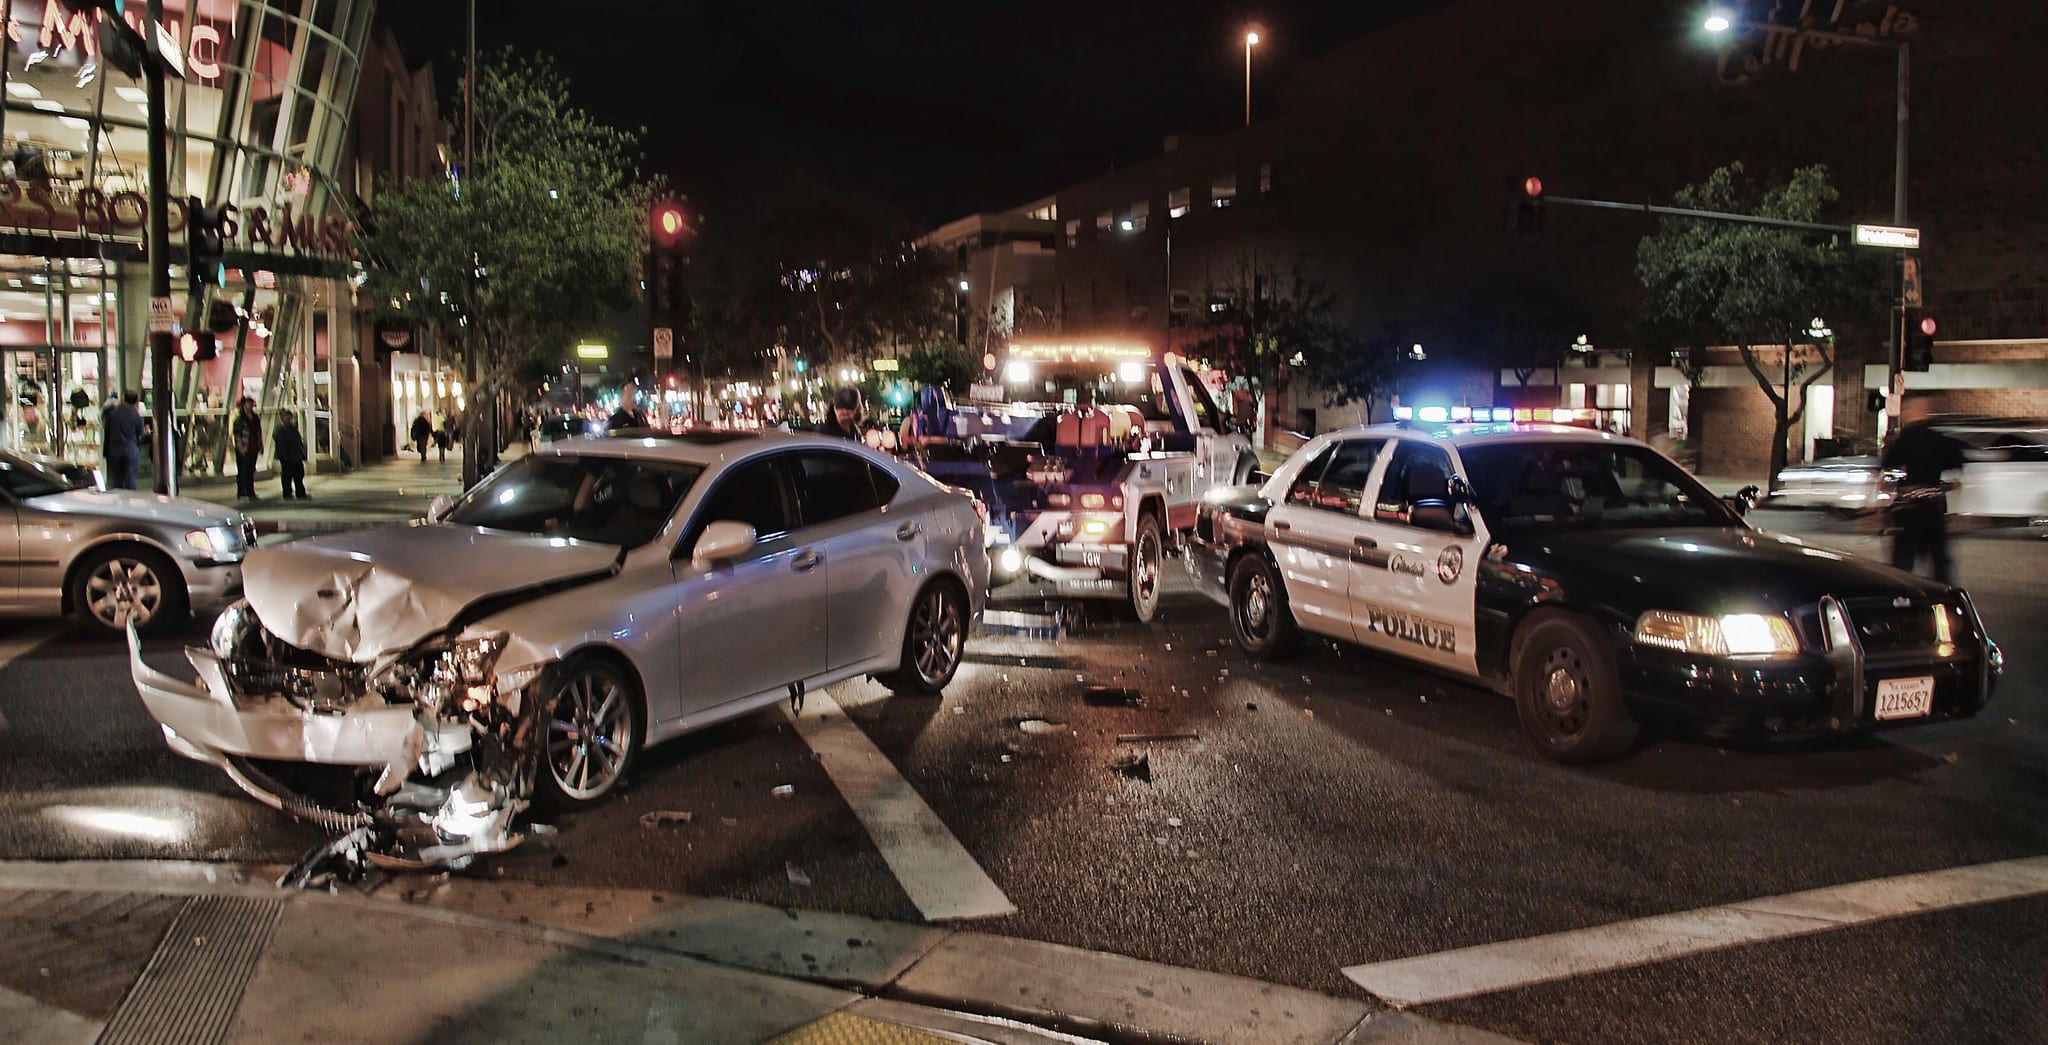
Second, look at the declaration page if you have collision coverage. If so, the insurance carrier should likely pay out the car in its entirety or pay a large portion of it out. In many circumstances, insurances will not pay full value of it. This is where you can investigate Mini-Tort coverage. If you are NOT at fault, you are able to get up to $3,000 from the other driver. It is as simple as calling the other driver’s information and demanding the $3,000. Make sure that you have proof that you are going to lose more than $3,000 to get that amount from them.
Uninsured/Under-insured
Third, there is UM/UIM coverage. Uninsured Coverage (UM) essentially means that if the other person does not have insurance and is at fault, you will be covered under your own policy for pain and suffering.
If the at-fault driver has low coverage of only $50,000 for his bodily injury coverage, but your injuries are very severe, there is something called UNDERinsured coverage (UIM). If you have UIM of $250,000, then between that and the at-fault driver’s coverage, you would be protected for $200,000 ($250,000 (Your UIM) – $50,000 (Their Policy)). You must exhaust the at-fault driver’s coverage limit (in this case, $50,000) before your UIM coverage kicks in. If your losses exceed that $250,000, then your UIM would cover another $50,000 (that you didn’t initially use because you had that amount from the at-fault driver).
Some of the tasks you must complete have deadlines and missing some of them can actually hurt your chances of financial recovery. Seeking legal advice is a wise choice, especially if your losses are severe.
Join the conversation!